Christian & Private School Insurance in Georgia
Coverage built for the risks Christian schools face every day — educators liability, student accidents, athletics, and transportation.
Christian and private school insurance in Georgia — including church-run schools and preschools — is what MinistrySure writes. Educators legal liability, student accident, abuse and molestation, athletics and field-trip liability, commercial auto for activity buses, directors and officers, property, and cyber are the lines a worship-focused church policy usually misses. We are the Loganville independent agency that reviews the school and the church together.
From student accidents to educators legal liability, your school needs protection designed for how schools actually operate — not adapted from a commercial template.
Last updated: February 2026
What coverage does your ministry need?
- Educators Legal Liability
- Student Accident Coverage
- Athletic & Activities Coverage
- Property Protection
- Workers Compensation
- Commercial Auto
- Directors & Officers (D&O)
- Abuse & Molestation
Where does Christian school insurance fall short?
Christian school insurance most often falls short in educators legal liability, student accident coverage, athletics and field trip exposure, and student transportation. Many schools rely on their church's policy, which typically wasn't designed for classroom operations, school-owned vehicles, or the specific claims that arise from educational decisions like discipline and expulsion.
- Educators legal liability. Claims from educational decisions — wrongful expulsion, failure to educate, improper discipline — require dedicated educators legal liability coverage, not just general liability.
- Student accidents. When a student is injured during class, PE, or an after-school activity, the school needs student accident coverage that pays the student's medical bills directly. This reduces the chance of a liability claim from the family. Our student accident calculator estimates the cost for your enrollment and activities.
- Athletics and activities. If your school has sports teams, field trips, or overnight events, those create separate exposure categories that need to be specifically addressed in the policy.
- Transportation. Schools that own or lease buses and vans need commercial auto coverage rated for student transportation — not just a church vehicle policy. Brotherhood Mutual provides dedicated commercial auto coverage for ministry vehicles.
- Church vs. school policy gaps. When a school operates under a church's policy, we review both to confirm the school's exposures are actually covered — not just assumed to be.
We review your school's coverage alongside your church's policy — because the gaps between them are where claims happen.
Board-Ready Evaluation Standards
What insurance does a Christian school need in Georgia?
A Christian school operating on a Georgia campus needs seven foundational coverage pillars. When trustees and business administrators audit their program, these are the core requirements and common policy gaps:
1. Property Coverage at Full Replacement Cost
~85% of Annual PremiumBuilding replacement value (TIV) accounts for roughly 85% of a school's total insurance premium. Insuring classrooms, gymnasiums, chapels, and cafeterias requires dedicated replacement cost valuation with agreed value terms to avoid severe co-insurance penalties after wind, hail, or fire damage. Learn more in our guide to Christian school insurance cost in Georgia.
2. Commercial General Liability (CGL)
Premises & Daily OperationsCovers slip-and-fall injuries, playground accidents, visitor incidents, and school-sponsored events on and off campus. Standard commercial general liability forms, however, explicitly exclude abuse claims and educational administrative decisions, requiring dedicated endorsements.
3. Governance & Administration: ELL vs. D&O vs. EPLI
Critical 3-Way DistinctionSchool boards frequently confuse these three administrative coverages:
- Educators Legal Liability (ELL): Protects teachers, administration, and the board against educational claims — wrongful expulsion, academic disputes, IEP/accommodation disagreements, failure to educate, and student disciplinary appeals. Standard D&O policies exclude educational decisions.
- Directors & Officers (D&O): Protects board trustees and leadership against financial governance claims, breach of fiduciary duty, and ministry management disputes.
- Employment Practices Liability (EPLI): Protects the school against employment-related lawsuits — wrongful termination, discrimination, harassment, and wage disputes under staff contracts.
4. Abuse and Molestation Coverage
Separate Aggregate Limit RequiredEvery youth-serving Christian school must carry dedicated abuse and molestation coverage with a separate standalone aggregate limit. Generic commercial brokers often sub-limit abuse or write defense costs inside the policy limit. In specialized ministry programs placed with carriers like Brotherhood Mutual, legal defense is paid outside the limit, preserving the full payout to protect the school's assets.
5. Student Accident Medical Insurance
No-Fault Medical PaymentsWhen a student breaks a bone in PE or on the playground, student accident coverage pays out-of-pocket medical bills and deductibles directly on a no-fault basis. Without it, parents must file a liability lawsuit against the school to trigger medical reimbursement. Calculate your school's estimated cost using our student accident calculator.
6. Athletics Participant & Commercial Student Transportation
Buses, Vans & TravelInterscholastic sports, PE classes, and off-campus field trips require athletic participant liability endorsements and commercial auto policies rated specifically for multi-function school activity buses and 15-passenger vans. Standard personal auto or basic church auto policies do not contemplate daily student transport routes or away-game travel radius.
7. Georgia Workers' Comp & Church-Policy Gaps
O.C.G.A. § 34-9-2 MandateUnder Georgia law (O.C.G.A. § 34-9-2), any employer with three or more regular employees must carry workers' compensation. Instructional faculty, coaches, aides, and cafeteria workers count toward this requirement. Furthermore, when a Christian school operates as a ministry of a church, relying on the founding church's insurance policy without explicit school endorsements creates dangerous blind spots. MinistrySure structures coordinated church-and-school programs to ensure seamless protection across all shared facilities.
Evaluate your school's coverage with our team
We review your Christian school's existing policies, building valuations, and program endorsements — providing an objective, board-ready assessment.

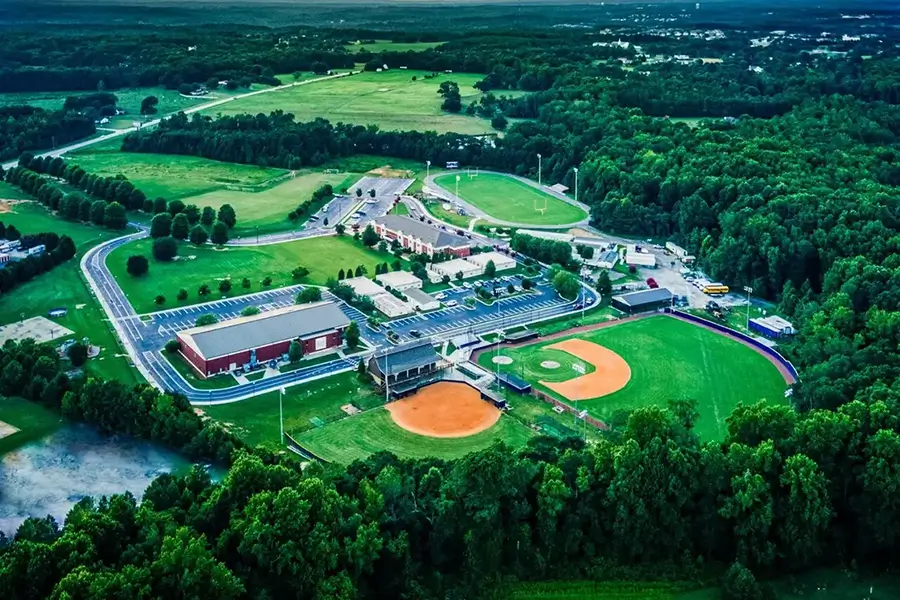
Campus facilities create distinct exposures
Cafeterias, gymnasiums, science labs, and playgrounds each carry specific liability and property risks. Food safety, athletic injuries, and equipment damage need to be addressed in your school's coverage — not assumed under a church umbrella policy. Those buildings are also the biggest line on the bill: see what Christian school insurance costs in Georgia and why roughly 85% of it is property.

Athletics and activities
Sports teams, PE classes, and after-school programs need participant accident coverage and specific liability endorsements.

Children's programs
Before- and after-school care, nursery programs, and youth ministry all require abuse and molestation coverage with carriers who understand prevention requirements.
What Christian school leaders say about MinistrySure
“Mike and the MinistrySure team have been with us for years. He shoots straight, picks up the phone, and works through whatever challenge comes with running a small Christian school. The administrative team is just as responsive. Five stars.”
Georgia Christian School Coverage Check
Ten questions covering building replacement costs, educators legal liability, student accident, abuse limits, athletics, and activity vans. Two minutes, instant gap score, and a personalized board-ready PDF report.
Related coverage & costs
Schools that operate as part of a church need both policies reviewed together. Review how much Christian school insurance costs in Georgia and why roughly 85% of premium is driven by building replacement values. See our church insurance page, or explore coverage for camps and retreat centers if your school runs summer programs. Learn why a specialist matters for ministry insurance. Running a preschool or daycare? See church preschool insurance and church daycare liability insurance. In metro Atlanta? See Christian school insurance in Atlanta.
Christian school insurance questions answered
What insurance does a Christian school in Georgia need? +
Christian schools need property, general liability, educators legal liability, student accident, workers' compensation, and commercial auto coverage. Schools with athletics should add athletic participation coverage. If part of a church, policies must avoid coverage gaps between the two.
Is educators legal liability the same as general liability? +
No. General liability covers bodily injury and property damage claims. Educators legal liability covers claims arising from educational decisions — wrongful expulsion, failure to educate, discrimination allegations, or improper discipline. Christian schools face both types of claims and need both coverages.
Does our church insurance automatically cover our school? +
Not always. Many church policies exclude school operations or limit coverage for student activities, athletics, and bus transportation. If your school is listed on your church policy, we review it to confirm the school's specific exposures are actually covered — not just assumed to be.
How much does insurance cost for a Christian school in Georgia? +
Christian school insurance in Georgia typically costs between $10,000 and $45,000 annually for most campuses, and $45,000 to $100,000+ for large facilities with full athletics complexes and bus fleets. Roughly 85% of premium is driven by building replacement value (TIV), layered with educators legal liability, student accident, and abuse coverage.
Does a Christian school need abuse and molestation coverage? +
Yes — it's one of the most important coverages a school carries. Standard liability excludes abuse and molestation, including negligent-hiring and failure-to-supervise claims against the school. Limits should scale with enrollment and the age of students, and the coverage should pay legal defense outside the limit so the full limit is available for the claim.
What is student accident insurance and does our school need it? +
Student accident coverage pays medical expenses when a student is injured at school or during school activities — regardless of fault — which heads off many liability disputes with families. Schools with athletics or active PE and recess programs should treat it as essential, often alongside a separate athletic participation policy.
Does a Christian school need D&O and employment practices (EPLI) coverage? +
Yes. Directors and officers (D&O) protects the board for governance decisions, and employment practices liability (EPLI) covers claims by staff — wrongful termination, discrimination, or harassment. Schools have more employees than most ministries, which raises employment-claim exposure, so EPLI limits should reflect your headcount.
Does our school's athletics program need separate insurance? +
Often, yes. Many policies require athletic participation coverage for interscholastic or contact sports, which pays for student-athlete injuries and helps manage liability. Travel to games and tournaments also adds transportation exposure that should be reviewed before the season.
Are before-school, after-school, and daycare programs covered? +
Not automatically — extended-care and daycare operations add hours, younger children, and staffing that many base policies don't contemplate, and they raise abuse and supervision exposure in particular. If your school runs these programs, confirm they're scheduled on the policy. See preschool and daycare insurance.
Does workers' compensation apply to a Christian school? +
Yes — with three or more employees, Georgia requires workers' compensation, and a school's teachers, aides, and administrative staff all count. It covers job-related injuries to employees and is separate from the student accident coverage that protects pupils.
What insurance does a Christian school need for field trips and transportation? +
Owned buses and vans need commercial auto; when staff drive personal or rented vehicles for school trips, hired and non-owned auto fills the gap. Field trips can also raise general liability and student accident exposure, so it's worth confirming off-campus activities are covered before the trip.
Can a church and its Christian school be insured under one policy? +
Often yes, through a single ministry package — but the school's specific exposures (educators legal liability, student accident, athletics, transportation) must be explicitly scheduled, not assumed. We review church-and-school accounts together to make sure there's no gap between where the church coverage ends and the school's begins.
What is educational institution insurance, and does a Christian school need it? +
Educational institution insurance is the package of coverages a school carries beyond a basic liability policy — property, educators legal liability, student accident, abuse and molestation, commercial auto for activity buses, directors and officers, and cyber. A Christian or private school is an educational institution, so it needs coverage built for classrooms and activities, not the worship-focused policy a church alone carries.
Michael · Matthew · Gabe
Talk to an agent who understands Christian school insurance.
Related resources for Georgia Christian schools: Christian School Insurance Cost Guide · School Coverage Checklist · Christian School Insurance in Atlanta · Educators Legal Liability · Student Accident Insurance · Abuse & Molestation Coverage · Church Preschool Insurance · Church Daycare Liability Insurance · Student Accident Calculator · GAPPS Member School Insurance
Let's review your christian schools coverage
A coverage review starts with a conversation about how your ministry actually operates.